Meydan Free Zone · accounting support

Accounting & Bookkeeping for Meydan Free Zone Companies

Know what the business earned, spent and owes—not only what reached the bank. SAIF helps Meydan companies keep reconciled records, useful monthly reports and a dependable year-end file for tax, management and any audit request.

Business owner reviewing financial records in a small trading workspace
Sales, platform settlements, expenses and bank activity should tell one consistent story in the ledger.

The direct answer

What should accounting services cover for a Meydan company?

They should turn source documents into complete, reconciled books and reports that an owner can use. The core work is recording transactions, reconciling bank and payment-platform balances, reviewing receivables and payables, closing each period and preparing financial statements. VAT and Corporate tax analysis use those records but are separate tax tasks.

A Meydan licence does not replace accounting records, and an online sales dashboard is not a general ledger. The right process depends on whether the company provides services, trades goods, sells through marketplaces or is funded by its owner. We agree the reporting outputs and responsibilities at the start.

Three distinct tests

Keep the books, check the audit request, assess the tax position.

The rules do not collapse into one blanket “free-zone exemption” or automatic annual audit upload.

01 · Meydan company records

Accounting records are required.

Clause 42.2 of Meydan’s Companies and Licensing Regulations requires records that explain transactions and disclose the company’s financial position with reasonable accuracy. Clause 42.1 also calls for financial statements.

Maintain the records even if trading is light or has not begun.
02 · Audit and authority

Respond to the actual request.

Under clause 42.1, audited financial statements are to be submitted within 30 days of an authority request. A bank, investor or the Corporate tax rules may create a separate audit need. Check the company’s current notice and period.

03 · Tax status

Free-zone status is not automatic 0% tax.

Assess VAT registration and the actual Corporate tax position. For Tax Periods beginning on or after 1 January 2025, Ministerial Decision 84 of 2025 requires a QFZP to prepare and maintain audited statements.

QFZP assessment →

Monthly accounting scope

What SAIF can take care of—and what we agree upfront.

We define the handover, approval cut-offs, reporting rhythm and any separate tax or software assignment in the proposal.

01

Daily transactions

Record sales, receipts, supplier bills, expenses, credit notes and owner-funded payments in the correct company and period. Keep source documents linked to the entries.

02

Bank and payment platforms

Reconcile every bank account and payment gateway. Identify fees, refunds, amounts held by platforms and foreign-currency differences before a net receipt is treated as sales.

03

Customers, suppliers and cash

Maintain aged receivables and payables, follow up unsupported balances and distinguish business cash from shareholder loans or reimbursements.

04

Monthly close and reports

Review the trial balance, cut-off, accruals and control accounts; produce an understandable profit and loss, balance sheet and cash position for management.

05

VAT and Corporate tax records

Keep tax codes, invoices and reconciliations consistent with the books. Identify transactions requiring separate VAT or Corporate tax analysis rather than letting software decide the treatment.

06

Year-end preparation

Close the ledger, assemble supporting schedules and prepare financial statements. If an independent audit is needed, the auditor’s appointment and work are separately scoped.

Different operating models

The licence can be the same; the records are not.

Bookkeeping must reflect the transactions the company actually makes.

Online sales

Marketplace orders, delivery evidence, refunds, platform charges and bank settlements must reconcile. The bank deposit alone may be net of several different items.

Consultancy

Connect fees to contracts, work performed and invoice timing. Track customer advances, unbilled work, subcontractor costs and overseas clients separately.

Trading and imports

Maintain inventory movements, purchase costs, shipping records, supplier balances and foreign-currency payments. Resolve stock and goods-in-transit differences at period end.

Owner-funded start-up

Record licence costs, capital, shareholder loans and expenses paid personally. A business with no sales can still have accounting transactions and reporting duties.

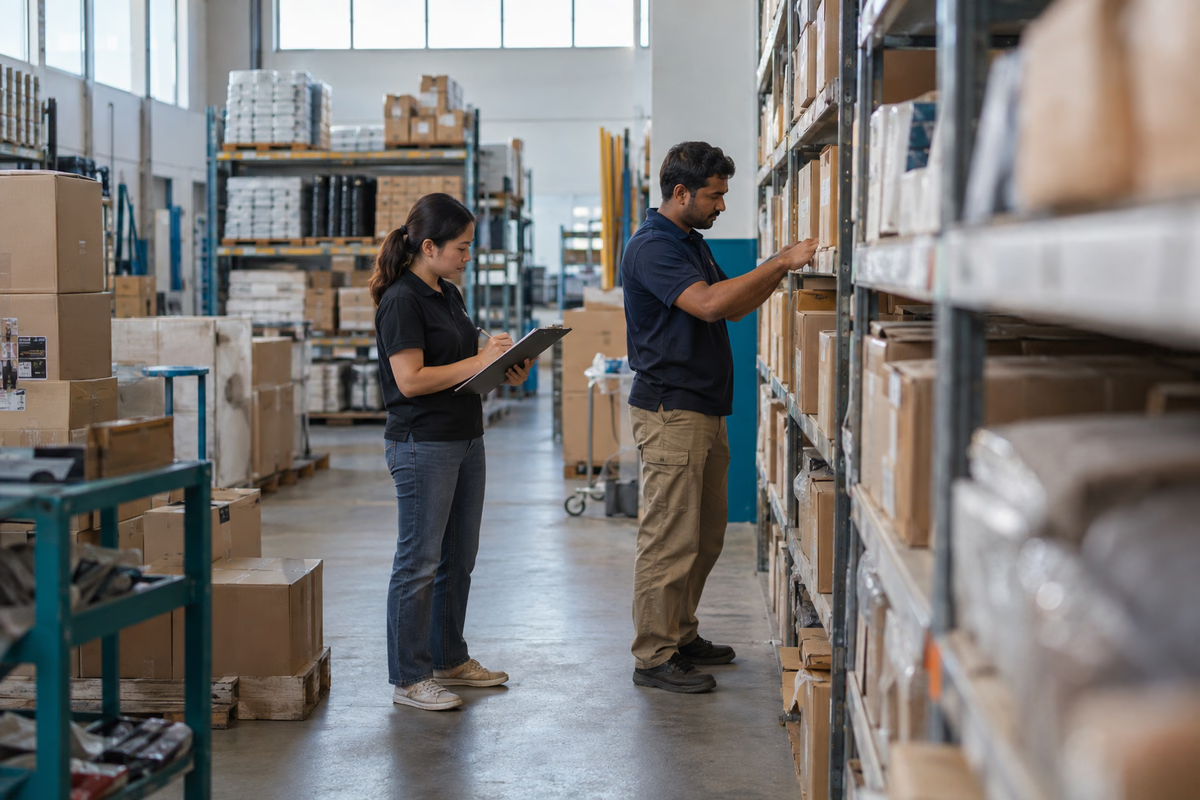
Warehouse staff checking physical stock against inventory records
For trading businesses, stock counts, supplier invoices and goods in transit should reconcile with inventory and cost of sales at year-end.

A practical example

Why is a marketplace bank deposit not the same as sales?

A Meydan online retailer may see one net payment from a platform. That amount can already exclude refunds, commissions, delivery charges and withheld balances. Booking the deposit as total revenue would lose the underlying sales and costs.

The monthly close should reconcile the platform order report to refunds and fees, then explain the amount settled to the bank. The remaining platform balance must agree to the ledger. This also gives the tax reviewer and any future auditor a traceable record.

01Orders & invoices

Gross sales and fulfilment evidence

02Adjustments

Refunds, platform fees and amounts held

03Bank & ledger

Settlements and outstanding balance reconciled

Working with SAIF

From the first review to a reliable year-end file.

The work is structured so the owner knows which decisions and documents remain outstanding.

  1. 01

    Review the starting position

    Share the licence, activity, financial year, current software, latest trial balance and status of VAT and Corporate tax registrations. We identify gaps before promising a close date.

  2. 02

    Agree the monthly scope

    Set transaction volumes, document handover, approval responsibilities, bank access method, reporting dates and which tax filings or software work are separate.

  3. 03

    Reconcile and report

    Post supported transactions, reconcile control accounts, investigate differences and issue the agreed management reports with questions requiring owner decisions.

  4. 04

    Prepare for year-end

    Close the books, preserve supporting records and coordinate the financial statements, tax analysis and any independent audit or authority response required.

A complete handover

Monthly bookkeeping should make year-end easier.

The output is more than a profit-and-loss statement. A useful handover includes a final trial balance, bank and tax reconciliations, aged balances, inventory or fixed-asset schedules where relevant, explanations of unusual items and the approved financial statements.

If Meydan requests audited statements, or the company needs an audit for Corporate tax, a lender or shareholders, the independent audit is a separate engagement. We assess auditor eligibility and independence rather than treating the accounting file as an audit report.

Financial statement preparation →

Frequently asked questions

Meydan accounting: practical answers

For owners choosing a bookkeeper, bringing records up to date or separating accounting from an independent audit.

01Does a Meydan Free Zone company need to keep accounting records?

Yes. Clause 42.2 of Meydan Free Zone’s Companies and Licensing Regulations requires records that show and explain transactions, disclose the company’s financial position with reasonable accuracy and support compliant accounts. Low activity does not make missing records acceptable.

02Does Meydan require every company to upload an audit report each year?

Do not assume a universal annual upload. Clause 42.1 requires financial statements and submission of audited statements within 30 days when the authority requests them. Check the company’s current portal notice and any separate tax, bank or shareholder requirement.

03Can a Meydan company use the 0% Corporate tax rate automatically?

No. A free-zone licence alone does not establish Qualifying Free Zone Person status or make every receipt Qualifying Income. The actual activities, income, substance and other conditions need review. A QFZP must prepare and maintain audited financial statements under the applicable tax decision.

04When must a Meydan Free Zone company register for VAT?

The UAE VAT test depends on taxable supplies and imports, not simply on the location of the licence. The FTA states a mandatory threshold of AED 375,000 over the previous 12 months or expected in the next 30 days, with a separate voluntary threshold. Review the business’s transactions before applying it.

05Is bookkeeping the same as an audit?

No. Bookkeeping records and reconciles the company’s transactions; an independent audit evaluates financial statements and supporting evidence and produces an auditor’s opinion. Any request for both services requires a separate scope and independence assessment.

06What documents do you need to start?

Usually the licence and incorporation documents, bank statements, sales and purchase records, expense evidence, payroll information, existing ledger exports, prior financial statements and VAT or Corporate tax filings. We tailor the list to the activity and current state of the books.

07Can you work with Zoho Books, Odoo or our existing ERP?

Yes, the accounting assignment can use a suitable existing system. SAIF also supports Zoho Books, Odoo and other accounting or ERP platforms. We review access, reporting and data quality before recommending a change; software implementation is separately scoped.

08How often will we receive reports?

The reporting rhythm is agreed in the engagement, commonly after each monthly close. The timing depends on receiving documents, approved entries and complete bank or payment-platform data. Reports should identify unresolved items, not silently conceal them.

09What affects the bookkeeping fee?

Transaction volume, number of bank accounts and entities, currencies, inventory, payroll, the quality of historic records, reporting frequency and tax work all affect scope. A catch-up project and ongoing monthly service should be quoted separately.

10Can a company with no sales skip bookkeeping?

No sales does not necessarily mean no activity. Licence fees, bank charges, owner funding, subscriptions, payroll or asset purchases may still need to be recorded. The reporting and tax position must be checked for that company.

Official references

Reviewed 15 October 2026. Check the company’s current portal notices and the rules applicable to its reporting period.

Start with the records you have

Let’s put your Meydan accounts in order.

Tell us the activity, financial year, software, number of transactions and current backlog. We’ll propose a defined bookkeeping and reporting scope.

Contact SAIF