Mainland and free-zone entities
UAE companies subject to Corporate tax need registration even where no tax is expected. A free-zone licence or low taxable income is not, by itself, an exemption from registration.
Explore the wider tax position →Eligibility · EmaraTax · Compliance handover
Start with the right entity, application and deadline. SAIF Chartered Accountants helps mainland companies, free-zone businesses and eligible individuals prepare their Corporate tax registration and follow through to the next compliance step.
Begin with legal form
An LLC, a freelancer and a foreign business do not necessarily have the same registration test. Start with the legal person—not just the trade name, licence or expected tax bill.
UAE companies subject to Corporate tax need registration even where no tax is expected. A free-zone licence or low taxable income is not, by itself, an exemption from registration.
Explore the wider tax position →The individual-business test uses aggregate business turnover exceeding AED 1 million in a calendar year. Wages and qualifying personal investment and real-estate investment income are excluded.
FTA guidance for natural persons →Residence, permanent establishment, UAE nexus and exemption rules need individual assessment. Do not use a standard LLC application without checking the facts and relevant registration category.
Corporate tax requires its own registration. Review the existing taxable-person profile first; avoid creating a duplicate entity simply because you need another tax type.
Registration is not return filing
A resident juridical person established under UAE law on or after 1 March 2024: within three months of incorporation, establishment or recognition.
Where the turnover threshold is exceeded: 31 March of the following calendar year.
Pre-March 2024 companies had a separate historical timetable. Foreign-managed entities and non-residents have different rules. Check the applicable category promptly; do not treat the old timetable as a new extension.
See FTA Decision No. 3 of 2024 for the complete category-specific timetable.
Apply by the deadline for your category.
Check the entity details and tax-period record.
Plan the separate annual compliance deadline.
Returns and any tax payment are generally due within nine months of the tax-period end. That does not extend the registration deadline. FTA Tax Returns guide →
Prepare a consistent application
We review the available records, identify inconsistencies and give you a tailored missing-items list before submission. The exact requirements depend on the applicant.
Valid trade licence and applicable branch licences; incorporation or commercial-registration records; memorandum, partnership agreement or equivalent constitutional documents.
Relevant owner and authorised-signatory identity records, ownership details and evidence of the signatory’s authority.
Business activities, registered address, contact details, financial year and relevant branch information. Match these to the supporting records.
Confirm the correct EmaraTax account and taxable-person profile. Keep control of business access; use an appropriate appointment for representation.
Check the current FTA service-card document list and registration user manual. Share identity documents securely, not through public links.
Applying online
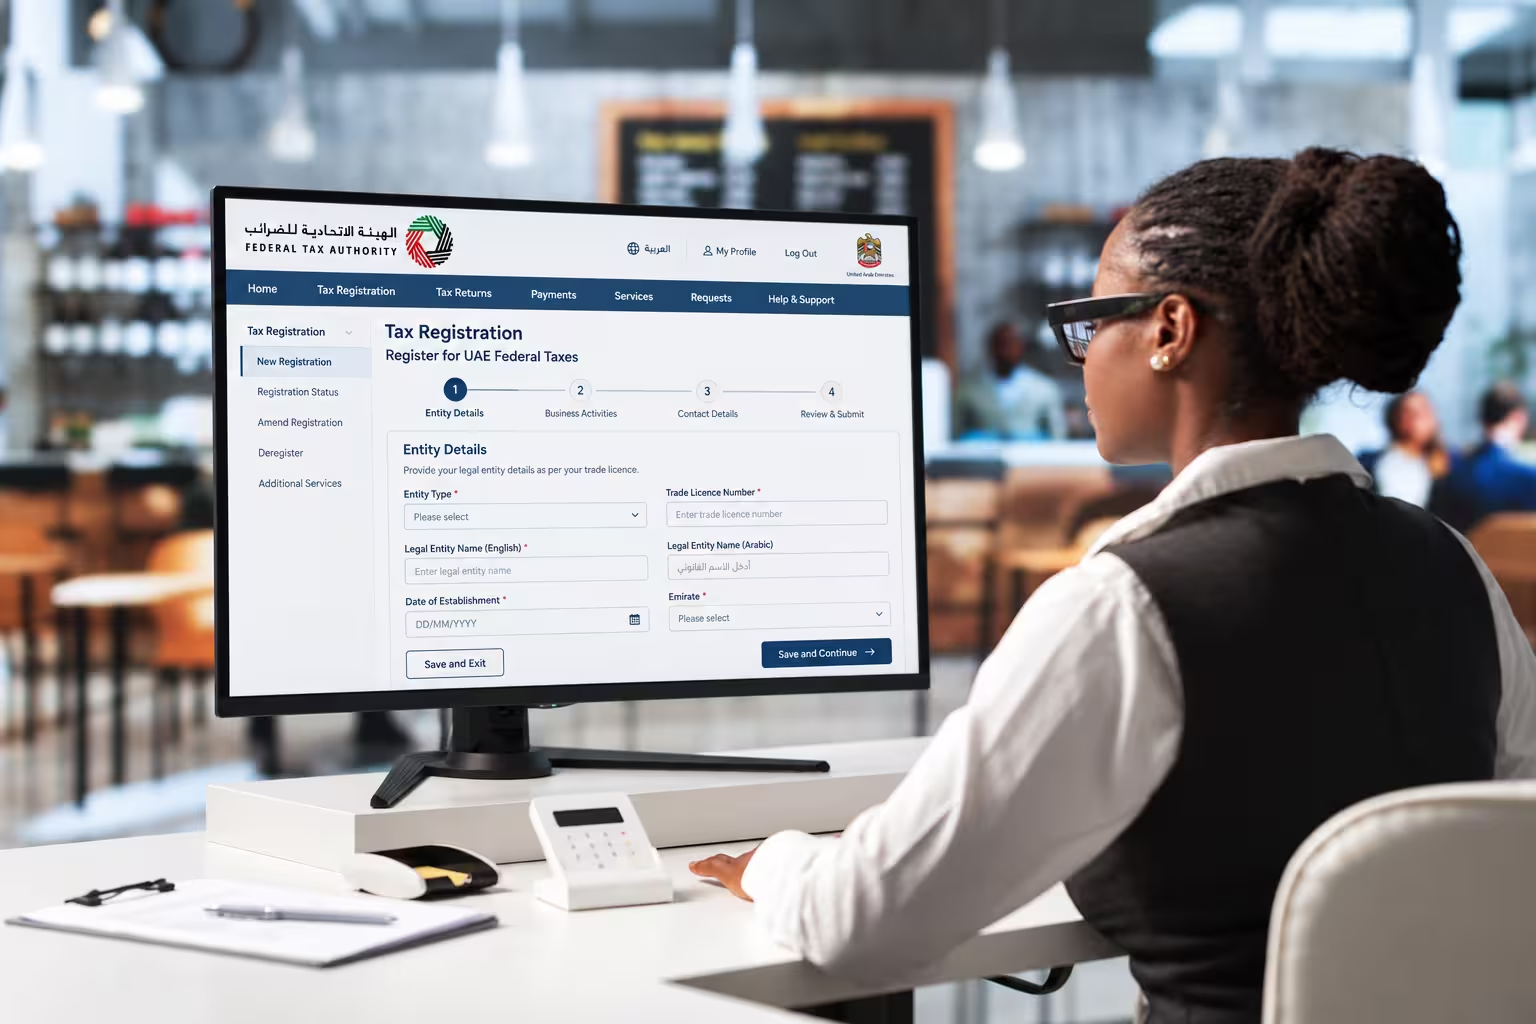
Start in the correct taxable-person profile and select Corporate tax registration. Check the legal entity, business activities, ownership, contact information and authorised signatory against your supporting documents.
Our role is to help organise and review the application—not to bypass the authority’s checks or guarantee approval.
Read the FTA registration user manual →How SAIF supports the application
Identify the legal person, activities, residence and registration deadline.
Match incorporation, ownership and signatory records to the application.
Review the EmaraTax application with management and retain acknowledgement.
Address FTA questions and check the registration details when approved.
We agree which entities are included, who supplies records, who approves the application and how follow-up questions will be handled. Flag ownership changes, multiple licences or an uncertain first financial year at the outset.
SAIF’s Tax Agency Number is 30004113. Where representation is required, confirm the appropriate appointment and responsibilities. Tax agency credentials and support →
If the deadline has passed
Late registration can attract an AED 10,000 administrative penalty. The FTA’s waiver initiative is conditional: eligible applicants must submit the first return within seven months of the first tax-period end; an annual declaration applies to relevant exempt persons.
This is not permission to postpone registration. Ask us to review the first tax period, application status and return readiness together. A paid penalty may be credited back if the conditions are met.
Read the FTA waiver conditions →The FTA registration service is free of charge. Its published estimate is 20 business days from receipt of a completed application. This is an authority estimate, not a guaranteed approval date.
Our professional fees reflect your company profile, entity structure, record quality and support needed. We separate registration assistance from accounting cleanup, technical advice and annual filing. Request a scoped proposal—there are no fixed plans.
FTA registration service details →Build an accounting and compliance calendar after approval. A tax certificate does not establish free-zone relief, approve your tax treatment or replace an annual return.
We can coordinate accounting and bookkeeping, Corporate tax advice and return-filing support under separate or combined agreed scopes.
If ownership, activities or legal status change, review whether the tax record needs updating. Closing a licence should also prompt a separate deregistration assessment.
Questions before you register
Use the Corporate tax registration service in EmaraTax for the correct taxable person. Prepare the entity and signatory records, complete the application, review it and submit. SAIF can assist with the eligibility review, preparation and follow-up under an agreed scope.
For a UAE LLC subject to Corporate tax, a loss or low profit does not itself remove registration obligations. Do not apply the individual-business turnover test to a separate incorporated company. Review any genuine exemption separately.
Free-zone companies subject to Corporate tax must register. Registration does not confirm Qualifying Free Zone Person status or entitlement to a 0% rate; those require a separate assessment.
An individual conducting UAE business activities generally comes within Corporate tax when aggregate business turnover exceeds AED 1 million in a calendar year. Wages and qualifying personal investment and real-estate investment income are excluded. Check the legal form: an incorporated company follows different rules.
Yes, if subject to Corporate tax. VAT registration does not automatically register the business for Corporate tax. Check the Corporate tax status in the correct EmaraTax taxable-person profile before starting another application.
For a resident juridical person established under UAE law on or after 1 March 2024, the application deadline is three months from incorporation, establishment or recognition. Other categories have different deadlines. Do not wait until the first tax return is due.
The FTA registration service is free of charge. Professional assistance is a separate service. SAIF quotes according to the entity structure, records, technical questions and follow-up required, without fixed packages.
The FTA service card estimates 20 business days after receipt of a completed application. This is not a guaranteed approval date. Incomplete records or further questions can affect the practical timetable.
Arrange a prompt review and registration application. Late registration can attract an AED 10,000 penalty. A conditional first-return waiver initiative may apply; check the first tax period and submission date rather than assuming every late applicant qualifies.
Branches of a UAE domestic juridical person are part of that legal entity and do not register separately for Corporate tax. Include relevant branch information in the head-office application. A foreign-company branch needs separate analysis.
Yes. A business can use EmaraTax directly. Professional help can be useful for unusual structures, uncertain eligibility or incomplete records. If representation is needed, agree the appropriate appointment rather than sharing passwords or one-time codes.
No. Registration is the starting point. Confirm the tax period, organise accounting records and plan the first return and any payment. Subsequent changes or business closure may require further applications.
Sources checked 28 September 2026. General service information; registration and relief eligibility depend on your facts.
Start with your business profile
Tell us the legal form, incorporation date, activities and current EmaraTax status. We will confirm the next information needed.
Request registration assistance →Continue on WhatsApp
