
FZCO audit obligation
Regulation 65.1 requires an FZCO to maintain records, prepare accounts and have them audited. It specifies at least six years of record preservation.
Other obligations may require longer retention.Dubai Silicon Oasis · DSO / DSOA
Audit and financial reporting support for technology businesses, SMEs and groups in Dubai Silicon Oasis. SAIF Chartered Accountants helps you prepare reliable accounts, resolve reporting questions and organise your annual audit.
Dubai Silicon Oasis audit and accounting
A growing technology company can have strong sales and still face difficult year-end questions: when to recognise a subscription, how to support development expenditure, or how to reconcile a payment platform with the accounts.
Our DSO audit service starts with these underlying transactions. We agree a practical evidence plan with your finance team, identify reporting risks and keep responsibilities clear from the initial request list through to final reporting.
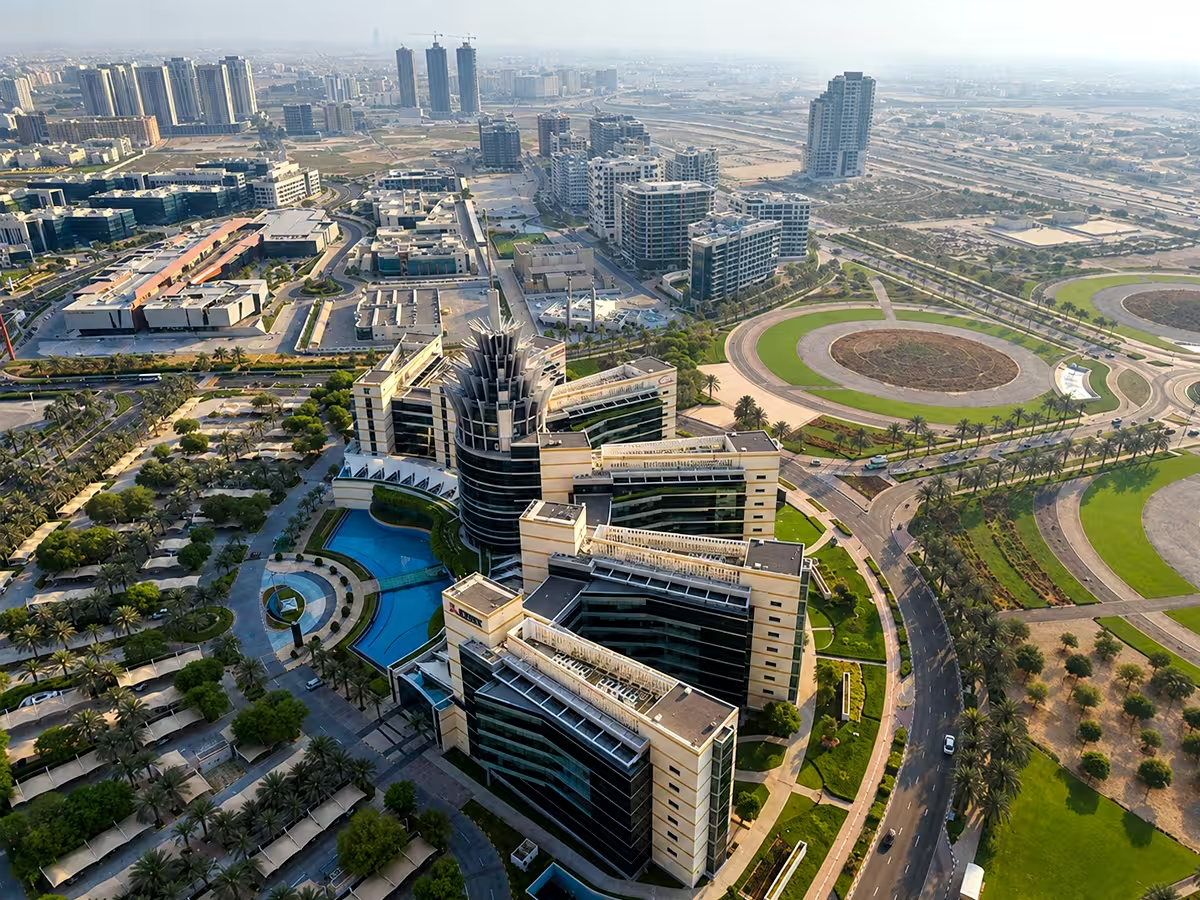
Dubai Silicon Oasis combines a technology-focused business environment with an integrated community. The familiar DSOA name remains widely used, while its current corporate regulations sit within the DIEZ framework. Check the authority and legal form on your licence rather than applying a checklist based only on your office address.
Whether you need your first annual audit, a group reporting package or help preparing incomplete records, the engagement should match the company’s actual reporting obligations and business model.
DSO audit requirements
Use the official DIEZ regulations and current authority instructions together. Confirm the reporting period and scope before setting a deadline.
Regulation 65.1 requires an FZCO to maintain records, prepare accounts and have them audited. It specifies at least six years of record preservation.
Other obligations may require longer retention.Regulation 67.3 requires directors’ approval and signature on their behalf by at least one director.
Plan time for review before the filing stage.Written auditor consent and independence are addressed in Regulations 65.7–65.8. Confirm the signing firm’s eligibility for the specific DSO engagement.
Keep appointment and scope documented.PLCs and branches have distinct provisions. Do not assume an FZCO timetable or reporting pack applies unchanged to them.
Check the legal form on the registration documents.Source: DIEZ Implementing Regulations 2023, Part 7, linked by the official DSO legislation page.
Choosing DSO approved or registered auditors
When comparing audit firms in Dubai Silicon Oasis, look beyond “approved auditor” wording. Establish who will sign the report, whether the firm is eligible for the assignment and how independence will be maintained.
Ask for the proposed engagement team, experience with your revenue model, a clear evidence request list and a realistic review timetable. Understand how accounting assistance is separated from independent audit work.
SAIF Chartered Accountants supports DSO businesses from its Dubai practice. We can discuss the reporting brief and confirm engagement acceptance before work begins. Authority-specific requirements should be checked for the actual signing firm.
DSO audit submission deadline
The published FZCO provisions below are not a substitute for checking current notices, amendments and instructions for your company.
The published text specifies these steps within 30 days after the FZCO financial year-end.
It then specifies filing the accounts and auditor’s report within 30 days after the accounts have been examined and reported upon.
Reconcile your timetable with the authority’s current directions. Keep the submission reference and follow up on outstanding queries.
Read the original provisions on printed pages 46–47. Do not treat the separate auditor-appointment provision as permission to delay preparation, or substitute a generic “four-month” deadline. Ask the authority to resolve any conflicting instruction.
Map the reporting period, audit milestones, filing requirement and renewal date separately. If a period is already overdue, share the actual notice with your adviser and agree a response; do not assume an extension or waiver.
Our Dubai Silicon Oasis audit services
Choose the work your company needs, with a clear distinction between the financial statement audit and additional advisory services.
An independent examination of financial statements, planned around material balances, reporting risks and your business model. Agree the reporting framework, auditing standards and intended users before fieldwork begins.
Establish the opening position, shareholder funding, incorporation expenditure and reporting period. Identify the evidence needed for early-stage contracts, development expenditure and significant estimates before the first year-end closes.
Review the trial balance, reconciliations and supporting schedules to identify gaps. Additional bookkeeping or accounts-preparation assistance is separately scoped and assessed for independence; management remains responsible for the records and approvals.
Coordinate head-office balances, group instructions and consolidation schedules. Identify the reporting entity and agree whether the assignment concerns standalone accounts, branch information or a package for group auditors.
Organise the signed accounts, corresponding auditor’s report and any requested supplementary information. Agree who submits through the company’s authorised account and who tracks requests for clarification.
Discuss recurring reconciliation issues, approval gaps or systems weaknesses. Internal audit, tax advice, due diligence and forensic investigations are separate assignments with their own objectives and engagement terms.
Sector-focused audit planning
Different business models need different evidence. These are examples of areas to discuss when scoping a DSO engagement.
Subscription periods, implementation milestones, support obligations, contract changes, deferred income and the connection between billing platforms and the ledger.
Project expenditure, time records, feasibility evidence, intellectual-property rights, investor funding, cash-flow forecasts and management’s assessment of future funding needs.
Inventory ownership and valuation, obsolete components, warranties, supplier rebates, goods in transit, foreign-currency balances and sales cut-off.
Payment-gateway settlements, marketplace commissions, refunds, customer deposits, unbilled work, subcontractor costs and cross-border receivables.
A planning illustration, not a rule that cash receipt determines revenue. Apply the relevant accounting framework to the contract.
Software and innovation businesses
For a subscription or implementation contract, the invoice date may not answer when revenue belongs in the accounts. Bring the agreement, deliverables, changes and acceptance evidence into the discussion. Where applicable, IFRS 15 provides the revenue-recognition framework.
Development expenditure also needs careful judgement. A project budget or software invoice does not by itself establish an intangible asset. Keep evidence distinguishing research from development and supporting any proposed capitalisation under the applicable framework, including IAS 38 where relevant.
For investor-funded businesses, explain the terms of each funding arrangement and support cash-flow forecasts. Discuss significant assumptions, commitments and subsequent events early rather than leaving them to the final accounts review.
DSO audit document checklist
These are common audit records. The engagement team will tailor requests to risks and materiality; this is not a mandatory authority-upload checklist.
Current licence, incorporation documents, memorandum and articles, ownership records, relevant resolutions, prior audited accounts and the confirmed financial year.
Final trial balance, general ledger, full-period bank statements, bank reconciliations, cash records, payment-processor balances and details for independent confirmations.
Customer agreements, invoices, credit notes, ageing reports, subsequent receipts, delivery or acceptance evidence and workings for accrued or deferred revenue.
Supplier invoices, accruals, prepayments, lease agreements, asset registers, inventory counts and valuation schedules. For software projects, include cost allocation and development-stage evidence.
Payroll records, employee-benefit calculations, shareholder loans, investment agreements, borrowings, guarantees, forecasts and significant contractual commitments.
Group structure, intercompany reconciliations, service agreements, relevant VAT returns, Corporate tax workings and supporting information for management fees or financing.
Use a controlled trial balance, track later adjustments and reconcile each supporting schedule to the ledger. Assign a person to each query and use the secure sharing channel agreed with the engagement team.
How the engagement works
Management prepares and approves the accounts. The independent audit team evaluates evidence and reports its opinion.
Review the licence, reporting period, appointment eligibility and authority instructions. Agree responsibilities, deliverables and fees in writing.
Close the trial balance, reconcile schedules and assign owners to missing items. Plan confirmations and inventory evidence early.
Perform risk-based testing, discuss accounting judgements and track queries. Management considers and approves proposed adjustments.
Complete the review, obtain management representations and approvals, and issue the auditor’s report when the necessary evidence is available.
Use the correct authorised service request, retain the submission reference and monitor the outcome. Respond using the controlled final version.
Financial statements and final deliverables
Confirm the reporting framework and a complete set of statements and disclosures for your entity. Under an IFRS engagement, discuss financial position, performance, cash flows, changes in equity, notes and comparative information; a trial-balance export is only a starting point.
The auditor’s report is separate from the financial statements. Any management-letter observations, group schedules or authority-form assistance should be identified in the engagement scope rather than assumed.
Before submission, check the legal name, period, approvals and consistency of all figures. Keep one final version and a record of who is authorised to file it. An upload acknowledgement is not necessarily final acceptance.
Audit fees and timing
To estimate a DSO audit fee, share the licence, reporting period, trial balance, prior report and a short explanation of the business. Mention stock, overseas operations, related parties, complex contracts or gaps in bookkeeping.
The work for a small consulting company with reconciled records differs from a software group with several revenue streams and funding arrangements. Transaction volume, systems, estimates, confirmations and record quality all affect the scope.
Ask the proposal to distinguish audit fees from any accounting cleanup, financial statement preparation, tax work and filing assistance. Agree how changes in scope will be handled. A low initial price is not useful if necessary work has been left undefined.
Set milestones for evidence readiness, fieldwork, queries, review and approval. Tell the team about investor or banking dates as well as authority requirements. We agree a realistic timetable after reviewing those dependencies.
Request a scoped DSO audit quotation →Audit, tax and control coordination
Free-zone incorporation is not a blanket tax exemption. Financial statement audit and specialist tax conclusions address different questions.
SAIF Chartered Accountants
Our UAE practice was established in 1994. We bring audit, accounting and tax disciplines together so your reporting conversations do not stop at a list of unexplained adjustments.
Discuss your DSO entity with our Dubai office at 1106, The Prism, Business Bay. Call +971 4 451 8600 or email info@saifaudit.com to outline the reporting period and support required.
Frequently asked questions
Practical answers for founders, finance teams and groups arranging a DSO engagement.
Speak to an audit specialist →For an FZCO, Regulation 65.1 of the DIEZ Implementing Regulations 2023 requires records, accounts and an audit. Check the company’s legal form, reporting period and current authority instructions; PLCs and branches have distinct provisions.
Confirm the proposed signing firm’s UAE audit licence, professional registration, independence and experience with your business model. Ask the authority to confirm any additional acceptance requirement for your specific engagement. Approval in another free zone is not proof of DSO eligibility.
Ask DSO/DIEZ through its official member portal or customer-support channel to confirm the proposed auditor’s current eligibility. A list reproduced on a commercial website may be incomplete or outdated. Obtain confirmation for the actual signing firm rather than relying only on a trading name or logo.
The deadline section on this page separates the FZCO preparation and audit stage in Regulation 67.5 from filing under Regulation 67.6(b). Confirm the timetable against current authority instructions. Do not use a generic three-, four- or six-month deadline without checking its basis and applicability.
No revenue does not mean there are no transactions or reporting obligations. Capital, licence fees, rent, bank charges and shareholder balances may still need accounting. Check the entity’s status and obtain written confirmation before relying on any exemption or relief.
Confirm its first reporting period, opening capital and funding, incorporation costs, contracts and bank activity. Establish bookkeeping and document retention from the start. A first-year audit also needs evidence supporting the opening position and significant accounting estimates.
We can scope an engagement around technology-company transactions, including recurring fees, project milestones, development costs and group charges. Share the main contracts, accounting policies and system reports so the team can identify the evidence and specialist input required.
Begin with the licence, financial year, prior accounts and trial balance. Prepare the six record groups listed on this page, then use the tailored request list agreed with the audit team. Documents submitted to the authority are not necessarily the same as the evidence used during the audit.
No. A system can organise transactions and reports, but balances still need reconciliation and evidence. Check opening balances, access controls, adjustments and links to billing, payroll and payment systems. An exported profit-and-loss report alone is not a complete audited financial reporting package.
Fees depend on the scope, transaction volume, revenue arrangements, systems, group balances, inventory and record quality. Request a written proposal distinguishing the independent audit from any bookkeeping, financial statement preparation, tax work or submission assistance.
Agree milestones after the records and scope have been reviewed. Missing schedules, delayed confirmations, complex estimates and unanswered queries can affect completion. Start early enough to accommodate review and management approval, and keep authority processing separate from the audit timetable.
No. The audit opinion depends on the evidence and financial statements. Authority acceptance and licensing decisions are separate matters. Early planning and a complete reporting pack support the process but cannot guarantee either outcome.
No. Free-zone incorporation alone does not establish a company’s entitlement to the Qualifying Free Zone Person treatment. Obtain a separate assessment of the applicable conditions and income. Audit, Corporate tax return preparation and transfer pricing analysis have distinct scopes.
Share the previous reports, opening balances, engagement status and any authority notice. Allow time for appointment formalities, professional communication and outstanding-period work. Confirm the required action with the authority rather than assuming an extension or automatic waiver.
No. The annual financial statement audit addresses the financial statements and an independent opinion. Internal audit reviews selected risks, processes and controls against an agreed plan. One does not automatically replace the other.
Further reading
 Audit
Current Dubai Silicon Oasis and DIEZ audit guidance covering auditor appointment, annual accounts, filing, independence and Corporate tax coordination.
Read insight ↗ Accounting
A practical UAE review of ERPNext configuration for VAT, Corporate tax, audit trails and the phased eInvoicing rollout through accredited service providers.
Read insight ↗ Corporate Tax
Assess QFZP eligibility, qualifying income, excluded activities, de minimis, substance, audit and transfer pricing requirements under UAE Corporate tax.
Read insight ↗Official reference points
Page updated 16 September 2026. Confirm current authority instructions and any amendments for your entity before acting. This page provides general information, not entity-specific advice.
SAIF Chartered Accountants · DSO audit services
Share your licence, reporting period and accounting position. We will help define the preparation, scope and reporting steps.
Request a DSO audit proposal →Continue on WhatsApp
